Every few years the same thing happens. Prices fall, the news gets loud, and people who never planned for it sell at the worst possible moment. The people who did plan for it do almost nothing — because they decided in advance how much they were ready to sit through.
This article is not a forecast. Nobody times the market well, and anyone who says they can is selling something. It is about the one part you fully control: how your money is spread before anything happens.
Most people are less diversified than they think
Ask someone where their savings are and you usually get one answer. A bank account. One flat. One coin bought in 2021 and never touched since.
That is not a plan. It is a single bet. It can work quietly for years and then stop working in a month.
Being spread out means your money is not all reacting to the same event at the same time.
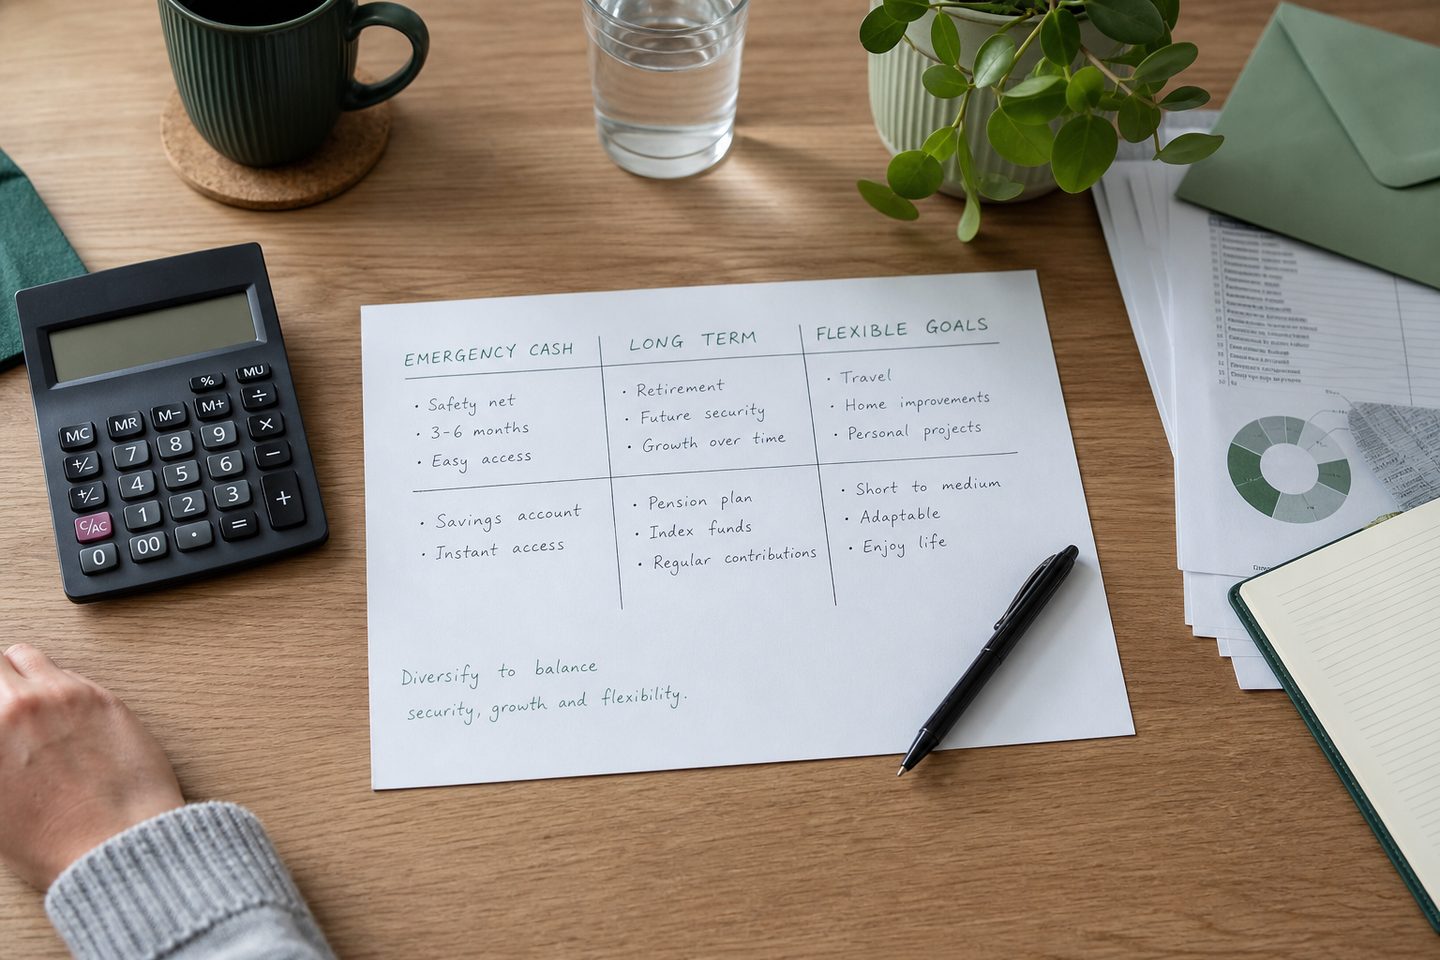
Three questions that decide your split
- What kinds of assets. Cash, shares, gold, property, crypto. They move for different reasons — and that is exactly the point of holding more than one.
- How long you can wait. Money you may need in six months does not belong in the same place as money you will not touch for ten years.
- How much you add each month. A small amount added every month does more for the result than most people expect. It also means you buy when prices are low without having to be clever about it.
Age changes the answer more than income does
At 30, a drop is an inconvenience. You have twenty years to sit through it, and everything you add afterwards is bought cheaper.
At 55, the same drop is a real problem, because you may need the money before it comes back.
This is why one piece of advice cannot fit both people. A plan that does not know your age is not a plan — it is a guess with confidence.
What income actually decides
Income does not decide how much risk you should take. It decides two other things: how fast you could rebuild if something went wrong, and how much you can add every month.
Two people holding the same €5,000 can need very different plans, if one of them adds €200 a month and the other adds nothing.
The part almost everyone skips
Choosing the split is the easy half. Keeping it is the hard half.
Prices move, so after a year your careful 60/40 is quietly something else. Almost nobody fixes it, because fixing it means selling the thing that went up — and that feels wrong every single time.
This is where automation earns its place. An algorithm does not feel wrong. It follows the rules it was given, in a calm month and in a bad one, which is the whole job.
Three things to do this week
- Write down where your money actually sits, in percent. Most people are surprised.
- Decide which part you could not afford to lose, and keep that part boring.
- Give the rest a time frame — and then stop checking it every day.
This article is for information only. It is not personal financial advice. Your capital is at risk and you may get back less than you put in.